Bennington
Merchant Cash Advance Small Business Warning for Local Owners
America’s fastest-growing source of funding for small businesses is also one of the least regulated. One man has waged a long, lonely fight to recoup its punishing cost.

Last updated:
Key points
- Merchant cash advances use daily bank withdrawals that carry effective interest rates ranging from 25% to over 200%.
- A business owner who thought he secured a $750,000 line of credit lost his home to foreclosure after falling into high-cost advances.
- An ongoing lawsuit against funder EIN Cap could mark one of the first major court trials over merchant cash advance misrepresentations.
NewsWK — Navigating commercial financing can present serious challenges for local enterprise owners in Bennington County and nearby communities. Quick online funding offers often promise fast relief during slow seasonal months. However, financial experts warn that high-cost funding arrangements can quickly trap growing companies in crippling debt cycles.
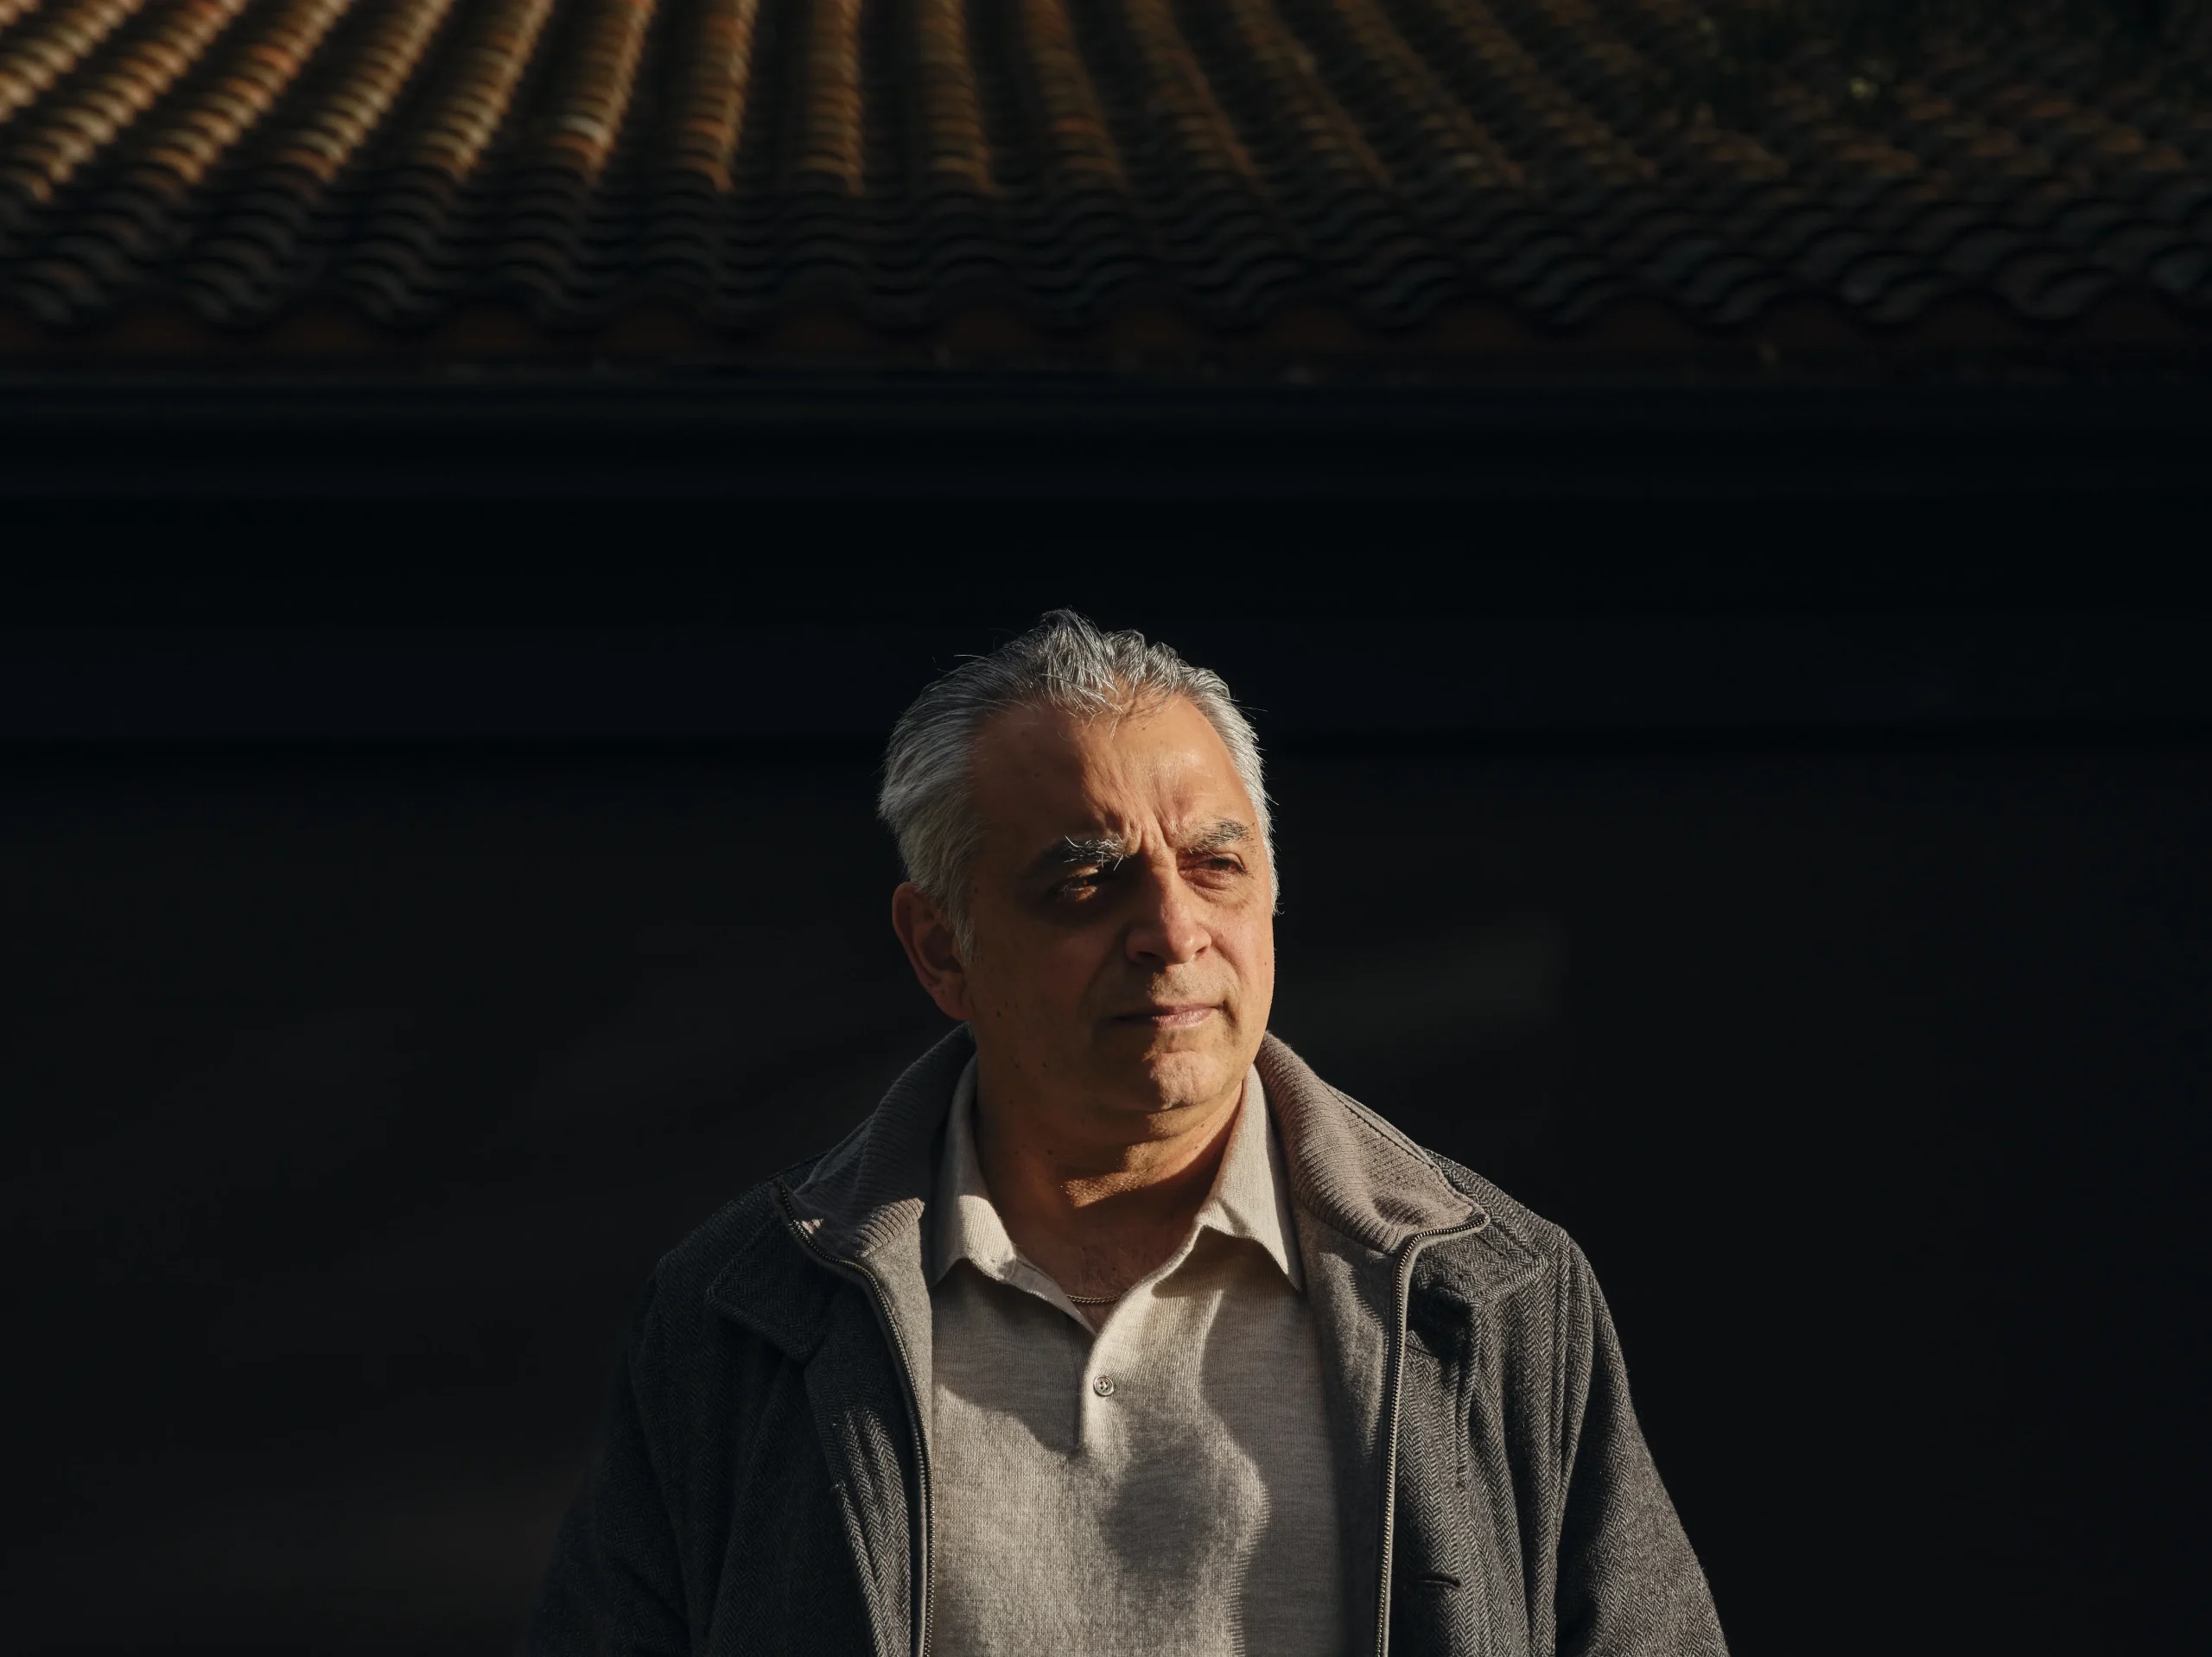
Recent Court filings highlight how fast-growing capital products can create devastating losses for small operations. For example, former aerospace engineer Vahe Shahinian learned this lesson the hard way. He spent 15 years building his event ticketing business, It’s My Seat. Ultimately, his experience illustrates the severe risks hiding behind aggressive marketing in commercial funding.
How does a merchant cash advance small business deal put owners at risk?
Merchant cash advances offer quick upfront capital in exchange for daily automated deductions from future sales. Unlike standard commercial loans, these financing arrangements carry few regulatory protections. Furthermore, fees can translate to effective annual rates between 25% and 200% or more. Consequently, high daily withdrawals can rapidly drain vital operating funds.
In 2019, Shahinian sought extra capital to scale his concert production work. A funding broker presented what appeared to be a $750,000 credit line. The offer promised interest under 9%. However, the terms required him to accept one-third of the funds first. In addition, he had to make daily payments of $3,600 to qualify for the full amount.
Shahinian dutifully made the automated daily transfers for 30 days. Then he continued paying for 40 days, and eventually 50 days. Still, the remaining promised credit line never materialized. Instead, he discovered the arrangement was a merchant cash advance rather than a conventional business loan.
What should owners know about small business MCA loans?
Small business MCA loans operate outside standard banking regulations. Funders structure them as sales of future receipts rather than traditional loans. Meanwhile, brokers often market these advances with promises of seamless refinancing. However, daily automatic debits can force struggling business owners into taking multiple secondary advances to cover basic operational costs.
Trapped by daily cash drains, Shahinian took out two additional cash advances totaling about $250,000. Subsequently, repaying those secondary contracts cost him nearly $400,000 in total fees and payments. As a result, the high costs completely wiped out his company’s operational profits.
Within weeks after signing the second advance, Shahinian owed more than $1 million to supportive friends and family. Eventually, the financial strain forced him out of his home of 16 years through foreclosure.
What key details surround the EIN Cap lawsuit?
Vahe Shahinian filed a lawsuit against commercial funder EIN Cap to challenge the transaction terms. Specifically, he alleges the firm used deceptive promises to trap his business in high-cost financing. Conversely, EIN Cap maintains in court documents that it offered only a merchant cash advance, never a line of credit or traditional loan.
Legal observers note that Shahinian’s lawsuit could become one of the first cases of its kind to reach a court trial. Therefore, the proceedings may set an important precedent. Judges could use the case to evaluate sales practices across the rapidly growing cash advance industry.
How do small business loan predatory practices impact local firms?
Entrepreneurs across Bennington, Shaftsbury, Manchester, and nearby Hoosick Falls rely on predictable cash flow to manage seasonal fluctuations. Consequently, high-cost advance agreements can destabilize local employers and retail shops. When daily bank withdrawals drain accounts, local businesses face immediate inventory shortages, payroll issues, and potential closure.
Therefore, business advisors recommend that local owners inspect all financing offers carefully before signing. Key warning signs in commercial funding offers include:
- Promises of future credit lines contingent on daily payment trials.
- Automatic daily bank withdrawals instead of monthly billing schedules.
- Lack of transparent annual percentage rate disclosures in loan documents.
- Brokers urging owners to stack multiple advances simultaneously.
How can local owners protect their business finances?
Local business owners should consult local bankers, certified accountants, or legal counsel before signing any short-term funding contract. Generally, transparent commercial lenders provide clear annual percentage rate disclosures and fixed monthly repayment terms. They also supply formal loan agreements. Ultimately, protecting local enterprises requires careful review of all fine print upfront.
Meanwhile, local business operators in Bennington County should evaluate safer options when seeking growth capital. For instance, owners can explore alternative community bank loans or regional development grants.
This article was produced with the assistance of AI and reviewed by our editorial team.
Related: Student Loan Default Collections: What Vermont Borrowers Must Know
Related: Exploring the Nicest Small Towns in Vermont for Bennington Residents